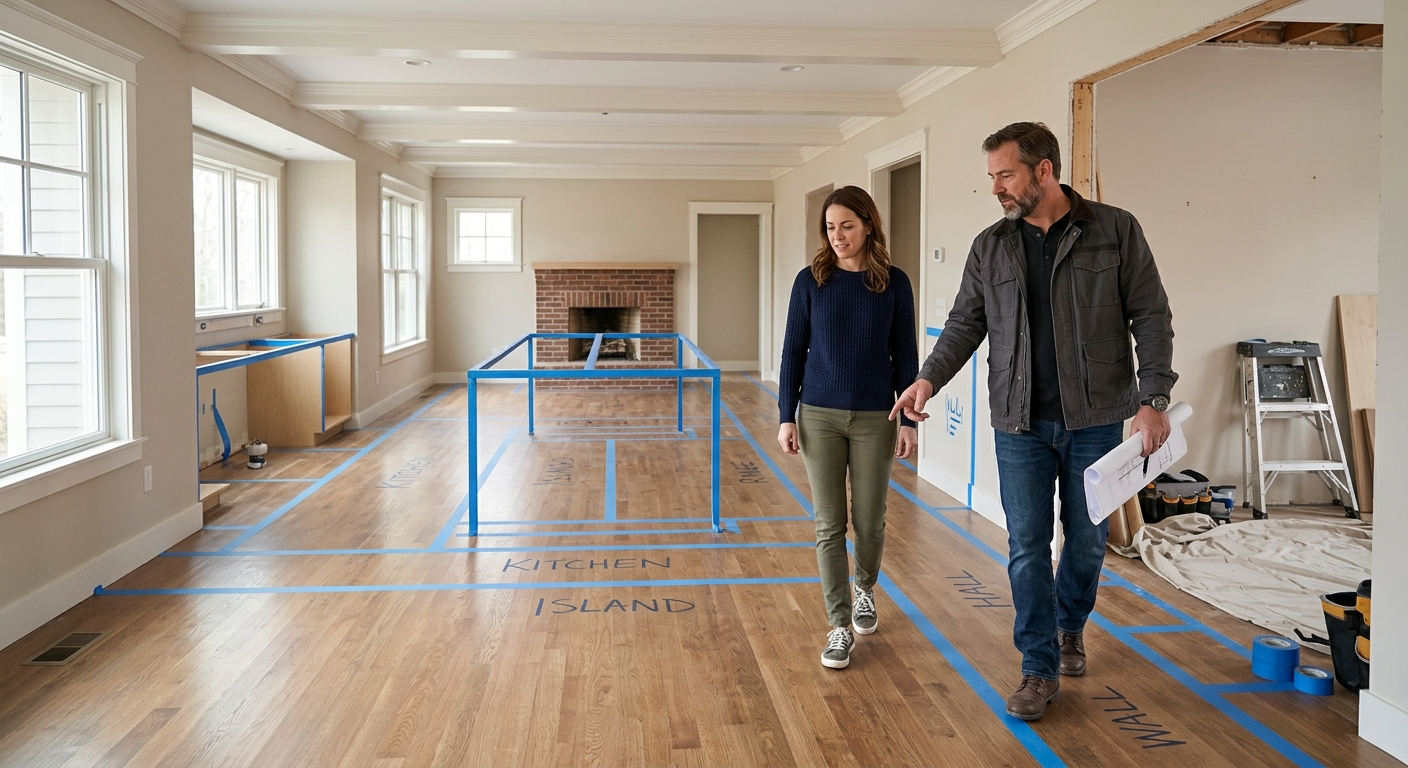

A fixed-price remodel contract generally places more pricing risk on the contractor for a clearly defined scope, while a cost-plus contract keeps more of the actual cost risk with the homeowner. Neither structure removes uncertainty. The real difference is how the contract handles incomplete information, price changes, allowances, hidden conditions, and the work needed to document costs as construction moves forward. The stronger choice depends on how complete the project scope is and how much visibility, flexibility, and cost certainty each side needs.
Start With What the Price Actually Covers
A fixed price is fixed only for the work the contract actually defines. The contract sum should be tied to drawings, specifications, selections, allowances, exclusions, and responsibility for permits, protection, cleanup, and other project requirements. Owner changes, concealed conditions, or work outside that definition may still change the price.
Within a clear scope, the contractor carries more of the risk that labor or material costs were underestimated. Outside that scope, the risk often remains with the homeowner. That is why the quality of the contract documents matters as much as the number on the proposal. A thin scope does not create certainty. It only hides the places where the price can move.
Fixed Price Rewards a Well-Defined Scope
Fixed-price work is most dependable when the design is developed, major selections are made, existing conditions have been investigated, and every bidder is pricing the same information. The contractor can estimate trade work, quantities, lead times, and coordination with fewer assumptions, while the homeowner gets a stronger baseline for financing and cash-flow planning.
The tradeoff is that certainty has a cost. A contractor may include contingency for risks that cannot be priced precisely, and changes after signing can require formal pricing and schedule adjustments. If the project is still full of unresolved decisions, a proposal can look fixed while relying on allowances and exclusions that leave the important uncertainty untouched.
Cost Plus Keeps Actual Costs Visible
In a cost-plus contract, the homeowner pays the allowable cost of the work plus an agreed contractor fee. The fee may be a percentage, a fixed amount, or another structure defined in the agreement. This approach can be practical when demolition may uncover significant unknowns, the design is evolving, or the team needs to start before every detail can be priced responsibly.
Cost plus can also give the homeowner useful visibility into trade invoices and purchasing, but that visibility is not automatic. The contract needs clear rules for documentation, reporting, approvals, and which expenses count as reimbursable costs. Without those controls, the homeowner carries changing project costs without a reliable way to understand the forecast.
The Fee Is Only One Part of Cost-Plus Risk
The headline fee does not explain the full cost-plus arrangement. The agreement should define how overhead, supervision, insurance, equipment, taxes, contractor-purchased materials, trade discounts, warranty work, and correction of mistakes are handled. It should also explain whether the fee is applied to change work, allowances, or other markups.
A percentage fee generally rises when the cost of the work rises, while a fixed fee behaves differently. Neither structure is automatically wrong, but the incentives and reporting expectations should be visible before work begins. Homeowners should be able to see the original budget, committed costs, money spent to date, pending decisions, and the current forecast without reconstructing the project from a stack of invoices.
A Guaranteed Maximum Price Is Still Not a Fixed Price
A cost-plus contract may include a guaranteed maximum price, often called a GMP. The GMP can place a ceiling on defined reimbursable costs and the contractor's fee, subject to the adjustments allowed by the agreement. Below that ceiling, payment is still based on actual allowable costs rather than a predetermined lump sum.
The protection is only as strong as the assumptions behind it. Allowances, exclusions, owner changes, contingencies, and unresolved scope can all affect whether the GMP moves. The contract should explain who controls contingency, what qualifies as an adjustment, and who receives any savings below the maximum. A ceiling with vague foundations can create the appearance of certainty without fully controlling the risk.
Match the Contract to Project Readiness
A fixed-price contract is usually easier to rely on after the team has resolved the decisions that materially affect labor, materials, and sequencing. A cost-plus structure may fit better when the existing home holds real unknowns, early work is needed to uncover conditions, or flexibility matters more than having a firm starting number.
Some projects use a limited preconstruction or investigation phase to reduce unknowns before moving into a fixed-price or GMP agreement. The point is not to force every remodel into one model. It is to choose a model that matches how much the team truly knows. When the contract promises more certainty than the documents can support, the disagreement usually appears later as a change order, delay, or scope dispute.
Administration Determines Whether Risk Stays Controlled
Both structures depend on disciplined administration. Fixed-price projects need a clear change-order process so the team knows what changed, why it changed, what it costs, and how it affects the schedule before the work proceeds. Cost-plus projects need timely invoices, commitment logs, budget updates, approval thresholds, and regular forecasts.
This is where communication protects design intent. A late cost surprise can force rushed substitutions, deferred scope, or compromises at the finish line. When the homeowner, contractor, and design team review cost movement and pending decisions together, they have a better chance to solve problems while options are still available.
Choose the Structure You Can Manage Clearly
Before signing, ask what is included and excluded, how allowances were set, how the contractor's fee is calculated, who controls contingency, what documentation will be provided, which costs need advance approval, and how changes affect price and time. If there is a GMP, ask what can adjust it and how savings are handled. Because the contract language controls the actual obligations, have appropriate legal and insurance advisers review it for the project.
The stronger contract is not automatically the one with the lowest starting number or the most flexibility. It is the one that matches the project's readiness and makes responsibility visible. When scope, cost reporting, decisions, and change procedures are clear, the team can manage risk without losing sight of schedule, quality, or the finished space.
Disclaimer: The content provided in this article is for informational purposes only and is not intended as financial, tax, or investment advice. JL Coates is not a financial advisor, tax consultant, or investment specialist. We recommend consulting with a professional financial advisor, tax specialist, or investment advisor to discuss your specific circumstances before making any financial, tax, or investment decisions based on this information. JL Coates assumes no responsibility for any actions taken based on the information provided in this article.